Tax information checked: 9 October 2026. General information, not a case-specific tax opinion. Updated: 15 October 2026.
Garant Business Consultancy reviews how a Dubai or UAE holding structure fits your international business, connecting ownership, banking, tax and management before you add entities or transfer assets.
Discuss on WhatsApp · Request a review
Check treaty eligibility for the country, income and residence position. A UAE licence does not guarantee treaty benefits or eliminate tax in the owner's country.
Provide your ownership chart, business model, entities, contracts and payment flows, together with available accounts, tax registrations and bank questions.
We examine ownership, operational roles, banking fit, UAE tax treatment, substance and reporting. Owner-country issues are identified for coordination with appropriately qualified local advisers; a UAE review is not a substitute for advice in every jurisdiction.
The proposal can cover a structure diagram, risk map and implementation sequence, with assumptions and unresolved questions. You receive a written scope and fee proposal before any work begins. Deliverables, timing and fees are agreed based on jurisdictions, documents and specialist input.
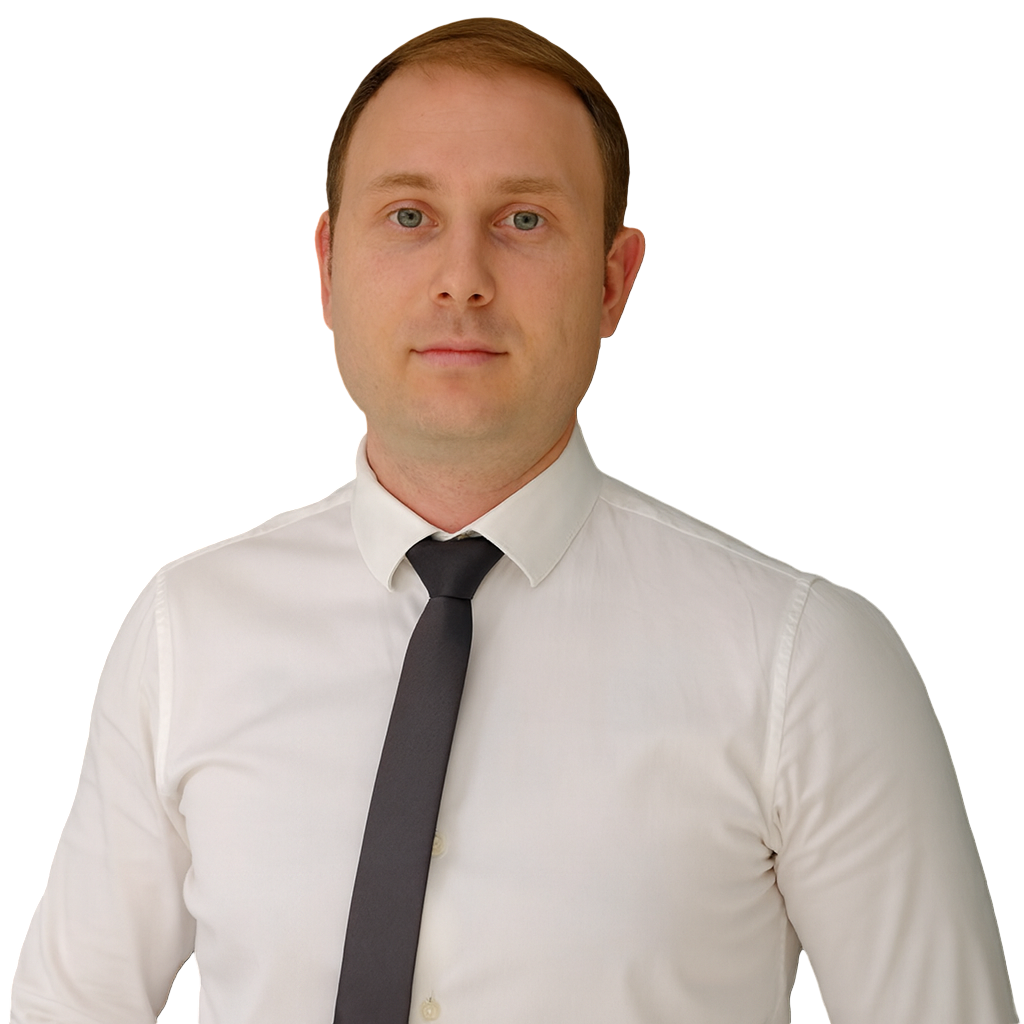
Marsel Shadmanov, Head of Corporate Services leads corporate-services delivery at Garant Business Consultancy. His work covers UAE market entry, company formation, banking preparation and mainland/free zone operational setup. Team allocation follows the engagement scope. Key People · Garant on LinkedIn.
Company formation · Banking solutions · VAT return filing and refunds · Company re-domiciliation · Tax domicile and residency
Why founders choose the wrong UAE setup · UAE corporate bank accounts in 2026 · UAE Corporate Tax 2025–2026 · Representative offices and tax exposure
Discuss on WhatsApp · Request a review
Source 3 comprises 3a–3c. Ministerial Decision 302/2024 applies to tax periods starting on or after 1 January 2025. Exemptions and special regimes depend on the facts and applicable tax period.
Business Logic Review
Identify activities, value creation and objectives.
Jurisdiction Mapping
Map owners and entities against commercial needs and jurisdictions.
Structure Design
Design ownership and operations around control, substance, tax, banking and flexibility.
Practical Risk Testing
Test bank onboarding, counterparties, reporting and documentation against the proposed structure.
Implementation Planning
Sequence corporate, contractual, banking and reporting work.
Ongoing Alignment
Reassess the structure when ownership, markets or operations change.
I had the pleasure of working with Garant Business Consultancy, and their team is incredibly professional. They provided clear and detailed guidance throughout the company setup process. Highly recommend.
I'm very satisfied with the service! Everything was handled quickly and efficiently, and the team was always available to help. Great quality and excellent support.
Need clarity on the right next step?
If this issue touches structure, banking, bookkeeping, or filing, it is usually better to resolve it early than correct it later. Message Garant on WhatsApp for a practical first view.
Does a UAE holding company pay tax on dividends from its subsidiaries?
Dividends from UAE resident juridical persons are generally exempt under Article 22, while foreign dividends require the applicable exemption conditions. Article 23 normally requires at least 5% ownership held, or intended to be held, for twelve uninterrupted months; aggregate acquisition cost of at least AED 4 million satisfies the minimum ownership and profit/liquidation entitlement tests, but does not remove the 12-month holding requirement or other exemption conditions. The subject-to-tax condition and other Article 23 requirements remain applicable; the asset-composition test applies to related-party participations. Disposal gains require the relevant holding period to have expired, so an intention to hold alone is insufficient. 2
What substance does a UAE holding company need?
Substance must match the activities and tax regime; there is no universal office-and-headcount formula. A QFZP must meet the applicable substance requirements for its activities, including the rules governing resources and permitted outsourcing. Decision-making evidence, records and banking requirements also matter.
Is a UAE free zone company suitable as a holding company?
It can be, but a free zone licence alone does not establish QFZP status or exempt every receipt. The income, activity, substance, audit, transfer-pricing and de minimis requirements must be checked together, with no election into the ordinary regime. Non-qualifying revenue must not exceed the lower of AED 5 million or 5% of relevant total revenue, using the statutory exclusions and calculations. Activity-specific compliance requirements may also apply. The ordinary regime and participation exemption may also need comparison.
Can a UAE company be managed from abroad and remain tax resident in the UAE?
A UAE-incorporated juridical person is generally a UAE resident person for Corporate Tax under Article 11, but overseas management can create additional foreign tax obligations. Dual residence, treaty rules and substance must be assessed separately. Incorporation alone does not guarantee exclusive UAE residence or treaty benefits.
How is a UAE structure viewed by banks?
Banks assess the owners, commercial purpose, activities and expected transactions rather than accepting a structure solely because it is registered. Contracts and source-of-funds evidence should explain who earns and receives each payment. A coherent structure supports an application but does not guarantee account opening or continued acceptance.
How long does a structure review take?
Timing depends on scope and document completeness. Multiple jurisdictions, historical issues or specialist advice may require more work. Agree a case-specific timetable and fee proposal before engagement.
Leave a request for a free consultation — we will contact you during business hours
While you wait, subscribe to us — we share cases and insights about business in the UAE


Leave your phone and we will call you back within one business day
The manager will contact you within one business day.
 +971 52 238 5765